
Loss of Income from Injury
Provides regular weekly or monthly payments if an accident or physical trauma prevents you from working.
Specialist Insurance · Personal Protection
Cover for Business Owners, Sole Traders & Self-Employed People
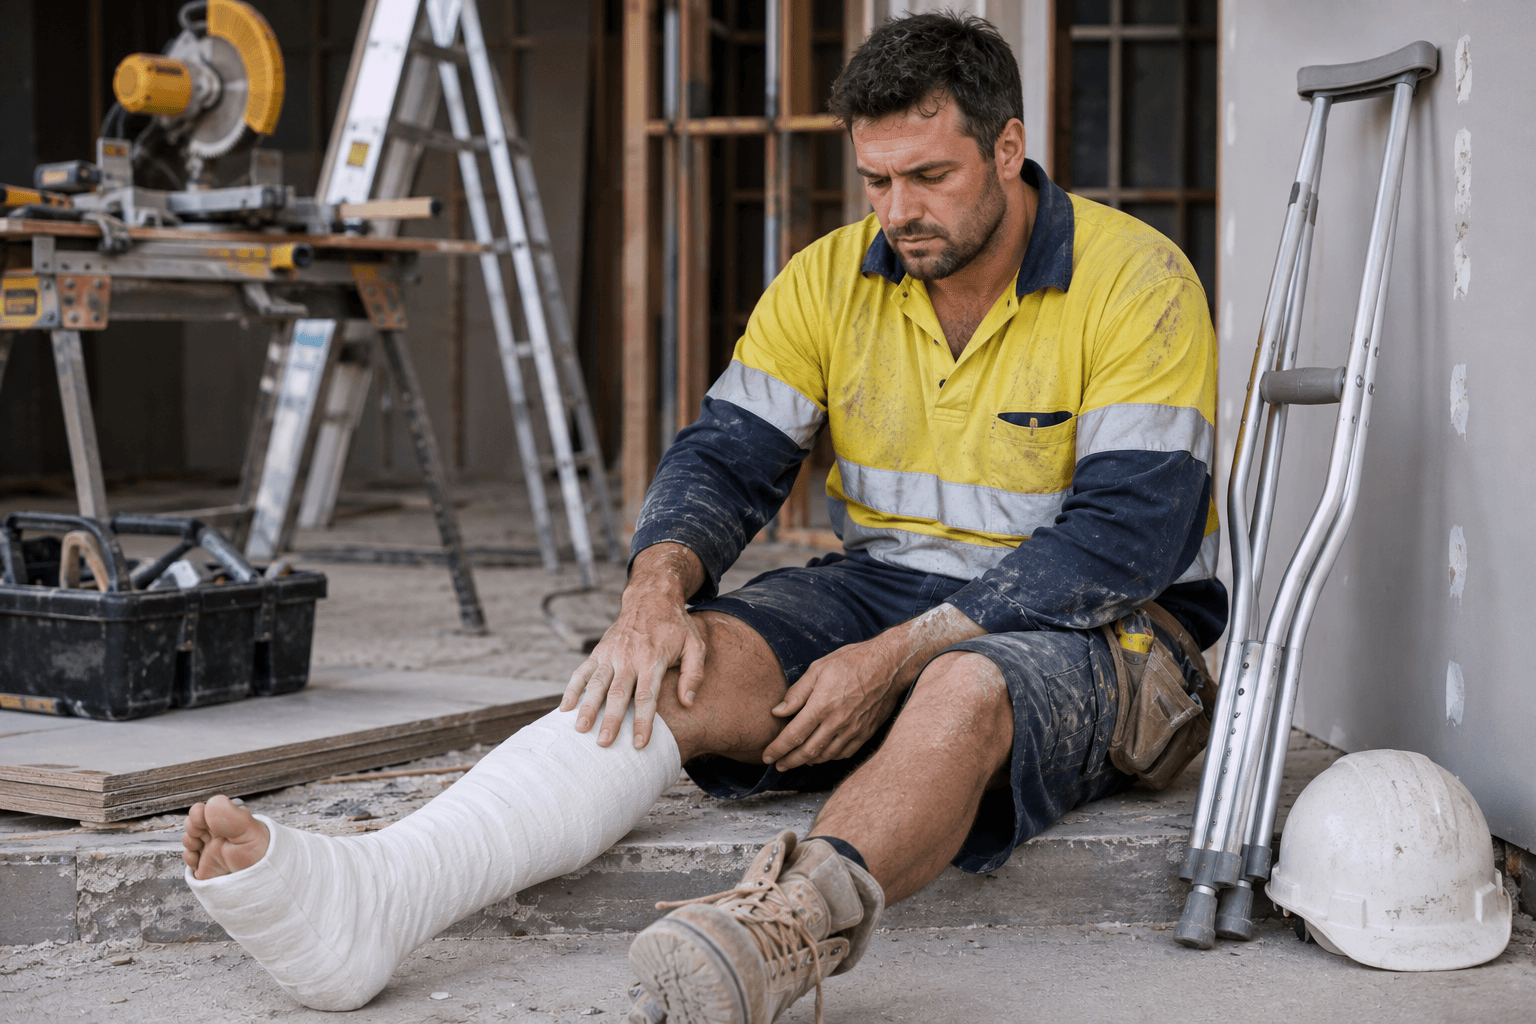
If you are self-employed or run a small business, an injury or illness can affect your ability to work and earn an income. Personal Accident & Sickness Insurance may provide benefits following certain injuries or illnesses, depending on the policy.
Access across leading Australian insurers and underwriting agencies, including:

Protecting Your Livelihood
Sole traders, contractors and business owners often don't have access to paid sick leave or workers' compensation. If an unexpected accident, slip, fracture or illness stops you from operating, Personal Accident & Sickness Insurance provides financial support so your mortgage, bills and business overheads continue to be paid.
100+
Underwriters
98%
Claims Success Rate
15-25%
Premium Savings
4.9
Google Review Rating
What Can It Cover?
Depending on the policy, cover may provide benefits following an insured accident or illness that prevents you from working. The benefits, waiting periods and policy conditions can vary between insurers.
Provides regular weekly or monthly payments if an accident or physical trauma prevents you from working.
Income support when a diagnosed sickness or condition keeps you off the job during recovery.
Fixed payments for permanent disablement or accidental death, supporting your family and business continuity.
Select policies can contribute towards ongoing fixed operational costs such as office rent and equipment leases.
Choose waiting periods (e.g. 7, 14, 28 or 90 days) tailored to your emergency savings buffer.
Cover durations ranging from 1 year, 2 years, or up to age 65 depending on underwriting eligibility.
Who May Consider It?
Self-employed individuals and business operators across diverse industries:
Cost Factors
Manual trades, physical work or high-hazard activities carry different risk profiles than office-based roles.
Your age and medical history can influence sickness cover eligibility, underwriting terms and pricing.
The weekly benefit amount selected (typically up to 85% of your verifiable gross weekly income).
Shorter waiting periods (e.g. 7 or 14 days) cost more than longer waiting periods (e.g. 28 or 90 days).
Whether the policy pays out for 1 year, 2 years, or longer terms for catastrophic disablement.
Choosing combined accident and sickness protection versus standalone accidental injury cover.
How We Help
It can be available to eligible self-employed people, business owners, contractors and others depending on the insurer.
Some policies provide both accident and sickness benefits. The exact cover depends on the policy.
There is no standard price. Premiums depend on the policy, occupation, benefits and other factors.
Typical waiting periods range from 7 days, 14 days, 28 days, to 90 days. A longer waiting period reduces the ongoing annual premium.
Yes. Many Australian insurers offer tailored accident and sickness policies specifically structured for trade and transport occupations.
Tell us about your work and we’ll explain the Personal Accident & Sickness options available.
